Your First $1,000: Why an Emergency Fund Comes Before Investing
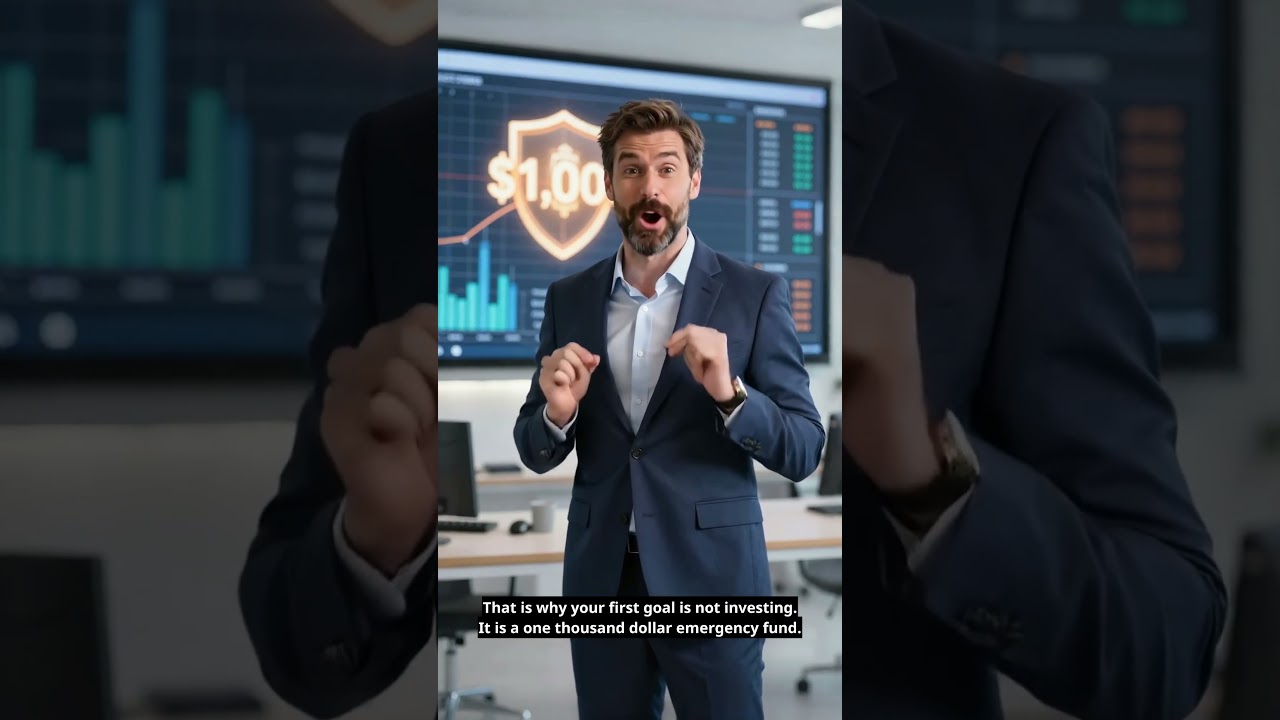
No savings? One flat tire can put you in debt for a year. That is the opening line of our Smart Money Life TIP video, and it makes a claim most investing advice skips: your first goal is not investing at all. It is a $1,000 emergency fund — built automatically, before you buy a single fund or stock. Here is the tip in full.
Key takeaways
- Most surprise bills are under $1,000 — but with no savings they land on a credit card at around 20% interest and turn into a year of payments.
- Your first $1,000 is a starter emergency fund: its job is not getting rich, it is keeping you out of debt.
- Automate $50 every payday into a separate high-interest savings account — in about ten months the buffer is done.
- Once the buffer exists, invest every extra dollar. Boring bills stop becoming emergencies.
🎁 Free companion for this guide
The free Money Pack pairs with this guide — and Pai Ledger HQ puts it into practice, starting with a free trial.
The bill that starts the debt spiral
A flat tire, a car repair, a broken appliance — the video puts the typical surprise at a few hundred dollars, and notes that most surprise bills are under $1,000. The bill itself is not the disaster. The disaster is the payment method: with no savings, it goes on a credit card at around 20% interest, minimum payments stretch it out, and a $600 repair quietly becomes a year of payments plus interest on top. One unplanned expense, paid for at the worst possible price.
Why $1,000, and why before investing
Why not invest first and keep the investments as the backup? Because the fund's job is different from an investment's job. The video puts it plainly: the fund is not for getting rich — it is for staying out of debt. A buffer of $1,000 covers the most common surprises in full, in cash, the day they happen. No interest, no payments, no spiral. It also protects your future investing: the saver who never has to raid a plan or reach for a card is the one who can actually leave investments alone to grow.
Put this into practice: Pai Ledger HQ
Watch your buffer grow payday by payday in Pai Ledger HQ, and grab the free money pack for the starter-fund worksheet from this tip.
Pai Ledger HQ is $6/mo, $61.20/yr or $120 lifetime — or get it inside the All Apps Pass ($72/mo) with every other app.
The build: $50 every payday, on autopilot
The method is deliberately boring. Automate a $50 transfer on every payday into a separate high-interest savings account — separate, so the balance is not staring at you from your everyday banking, and automatic, so it never depends on motivation. The video's calendar maths: at $50 a payday, the balance climbs through $200, $600, and reaches $1,000 in about ten months. The transfer fires on payday morning, before spending starts — pay yourself first is a slogan, but scheduling it is what makes it real.
What changes once the buffer exists
With $1,000 sitting ready, the character of a surprise bill changes completely: it becomes an inconvenience you pay and forget, not a debt you carry. That is why the video ends where it does — once the buffer is done, invest every extra dollar, and let the habit you built carry over: the same payday automation that built the fund becomes the investing contribution. And $1,000 is the starter fund, not the finished one — when you are ready to size the full three-to-six-month version, our emergency fund guide prices one essential month in three steps.
Put it into practice
Watch your buffer grow payday by payday in Pai Ledger HQ, and grab the free money pack for the starter-fund worksheet from this tip.
Get the free Money Pack Pai Ledger HQ
Or get every Pai Digital app in one plan: the All Apps Pass — $72/mo, $734.40/yr or $1,440 lifetime, with free trials on every app.
Frequently asked questions
Is $1,000 really enough of an emergency fund?
It is the starter fund, sized to the most common surprises — the video notes most surprise bills come in under $1,000. The full fund is three to six months of essential expenses; the $1,000 comes first because it stops the debt spiral while you build the rest.
What if I cannot spare $50 a payday?
Automate a smaller amount rather than skipping automation. The mechanism matters more than the number: a transfer that fires on payday, every payday, grows without decisions. Raise it when income rises — the finish line moves closer, it does not disappear.
Where should the $1,000 sit?
In a separate high-interest savings account: insured, reachable within days, and not invested. Money whose job is certainty should never ride the stock market — and keeping it at a different account than your daily banking stops casual raids.
How we make these guides
Every guide in this section started as a video on one of our YouTube channels, and the written version is checked against that video's own script before it is published. Every tip was first published as one of our own videos. Fee figures come from fund documents, account and tax figures from the CRA and IRS rules for the year named, and each tip links to the full guide behind it. We do not invent numbers: if a figure is not in the video or a source the guide names, it is not in the guide. When a rule changes, we update the guide — and the “last verified” date at the top of this page changes with it. Everything here is educational only — not financial, tax, legal or investment advice for your specific situation.
Recommended next reads
 Money & Savings
How to Save $10,000 in One Year: The Canada + US Plan
$10,000 in 12 months is $833 a month — or a smarter mix. The step-by-step savings plan from Smart Money Life: automate, cut the big three, add one income lever.
 Money & Savings
Emergency Fund: $9,600 or $19,200? How Many Months You Actually Need
Three months or six? Canadian Money Math #8 does the arithmetic: what counts as a month of expenses, who needs more, and where the fund should live.
 Money Tips & Tricks
 That Actually Work (2026): 14 Small Moves That Change Your Money
14 money tips and tricks from our guides and daily tip videos — the $1,000 buffer, the MER check, accelerated bi-weekly, the TFSA order — each linked in full.
Watch next
Prefer reading? Read the guide: How to Save $10,000 in One Year: The Canada + US Plan
Disclaimer: educational and informational only — not financial, tax, legal or investment advice. Figures and rules change and vary by province/state and personal circumstances. Consult a licensed professional for advice specific to your situation.
💬 Over to you
Have you built your first $1,000 yet? If yes, how long did the payday automation take — and if not, what's your payday amount going to be?
Share it in the comments below — every comment gets a reply.
Comments
Comments are moderated to keep this page clean: first comments and anything containing a link are checked by a human before they appear, and spam is blocked automatically. Your email is never shown — it only tells the moderator you are a returning reader.
Loading comments…