The 1% Fee Trap: How a Small Fund Fee Can Cost You $100,000+ Over 30 Years
A tiny 1% fee can quietly cost you over $100,000. That is the claim at the heart of our Smart Money Life TIP video — and unlike most scary money claims, the maths is simple enough to check on your own statement. This written version walks through the two-investor comparison, the third of the pot that disappears, and the three-letter fee almost nobody checks: the MER.
Key takeaways
- Two investors earning the same returns can finish a third apart — purely because one paid 2% in annual fund fees and the other paid almost nothing.
- On $100,000 growing for 30 years, the fee gap between a typical high-fee fund and a low-cost index fund can eat about a third of the final pot.
- The fee hides on your fund statement as the MER — the management expense ratio — a small percentage charged every year on your whole balance.
- Low-cost index funds often charge under 0.2%. You cannot control the market, but the fee is the one number you can control.
🎁 Free companion for this guide
The free Money Pack pairs with this guide — and Pai Ledger HQ puts it into practice, starting with a free trial.
Two investors, same returns, different endings
The video sets up the cleanest possible comparison: two investors, the same starting money, the same investment returns. Only one thing differs — what each pays in fees. One pays 2% a year, the kind of fee buried in many traditional mutual funds. The other pays almost nothing, the kind charged by low-cost index funds. Because everything else is identical, every dollar of the final gap is fee damage — not bad luck, not bad timing. Fees are the one drag that is guaranteed to show up every single year.
How a third of the pot disappears
A 2% fee does not sound like a third of anything. The trick is what it is charged on, and how often: every year, on your entire balance — including all the growth the balance has already made. So the fee compounds against you exactly the way returns compound for you. On $100,000 growing over 30 years, the video's comparison lands here: the gap between paying 2% and paying under 0.2% can eat roughly a third of the final pot — a six-figure difference on the title's terms, produced by a 'tiny' percentage nobody remembers agreeing to.
Put this into practice: Pai Ledger HQ
See every account and what each one costs in Pai Ledger HQ, and use the free money pack's fee worksheet to run your own MER check.
Pai Ledger HQ is $6/mo, $61.20/yr or $120 lifetime — or get it inside the All Apps Pass ($72/mo) with every other app.
Meet the MER: the fee hiding on your statement
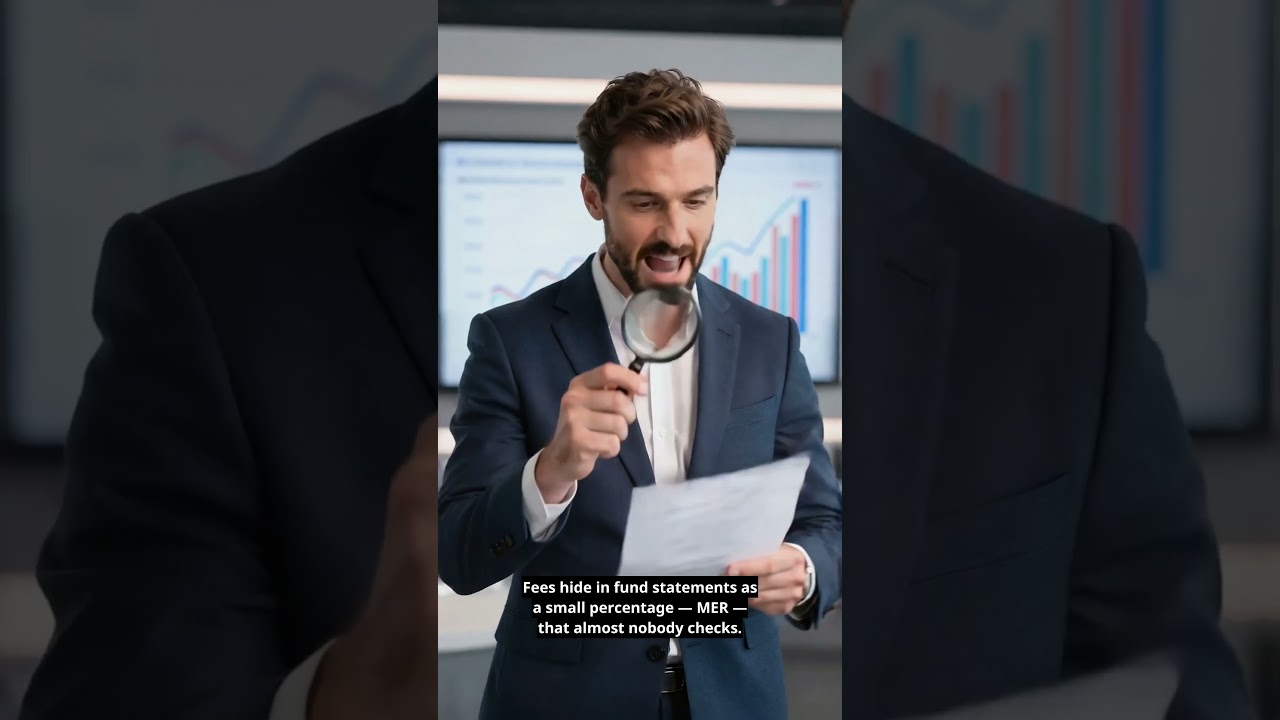
In Canada, the fee is printed as the MER — management expense ratio — the total annual cost of running the fund, expressed as a percentage of its assets and deducted quietly before your return is reported. US investors will see the same idea as a fund's expense ratio. The video's image is a magnifying glass over a statement, and that is literally the assignment: the MER is on your fund's documents, but it is printed small, quoted as a percentage so it feels abstract, and almost nobody checks it. A 2% MER on a $100,000 balance is $2,000 leaving in the first year alone — and more every year the balance grows.
The one number you can control
Markets will do what they do — nobody can schedule returns. But the video's closing point is the hopeful one: the fee is the one number you can control, starting today. Low-cost index funds often charge under 0.2%, and you keep the difference, compounding for you instead of against you. The action step takes ten minutes: find the MER on each fund you own, write the numbers down, and do the comparison our full investing guide walks through for beginners. Check your MER this week — then decide, with your eyes open, what you are paying for.
Put it into practice
See every account and what each one costs in Pai Ledger HQ, and use the free money pack's fee worksheet to run your own MER check.
Get the free Money Pack Pai Ledger HQ
Or get every Pai Digital app in one plan: the All Apps Pass — $72/mo, $734.40/yr or $1,440 lifetime, with free trials on every app.
Frequently asked questions
Where do I find my MER?
On the fund's own documents — the fund facts sheet and your account statements list the MER (management expense ratio) for each fund you hold. In the US, look for the expense ratio in the fund's prospectus summary. It is a percentage per year, charged on the whole balance.
Do higher fees buy better returns?
The video's comparison holds returns equal on purpose: whatever a fund earns, the fee comes off the top every year regardless. A higher fee is a guaranteed drag that the fund must overcome just to tie a cheaper one — which is why the fee is worth checking before anything else.
What fee should I aim for?
The video's benchmark is the low-cost index fund at under 0.2% a year. You may have reasons to hold something that costs more — but after this check, it will be a decision you made on purpose, not a default you never noticed.
How we make these guides
Every guide in this section started as a video on one of our YouTube channels, and the written version is checked against that video's own script before it is published. Every tip was first published as one of our own videos. Fee figures come from fund documents, account and tax figures from the CRA and IRS rules for the year named, and each tip links to the full guide behind it. We do not invent numbers: if a figure is not in the video or a source the guide names, it is not in the guide. When a rule changes, we update the guide — and the “last verified” date at the top of this page changes with it. Everything here is educational only — not financial, tax, legal or investment advice for your specific situation.
Recommended next reads
 Money Tips & Tricks
 That Actually Work (2026): 14 Small Moves That Change Your Money
14 money tips and tricks from our guides and daily tip videos — the $1,000 buffer, the MER check, accelerated bi-weekly, the TFSA order — each linked in full.
 Trading
How to Start Investing With Just $100 (2026 Guide)
No fortune needed: open the right account, buy a broad index ETF, automate a small weekly amount. The beginner investing guide from Smart Money Life.
 Economy
Protect Your Savings From Inflation in 2026: The Real-Return Check
If your savings earn 1% while inflation runs hotter, you are losing money safely. The one-subtraction real-return check and the ladder of fixes, Canada + US.
Watch next
Prefer reading? Read the guide: Money Tips & Tricks That Actually Work (2026): 14 Small Moves That Change Your Money
Disclaimer: educational and informational only — not financial, tax, legal or investment advice. Figures and rules change and vary by province/state and personal circumstances. Consult a licensed professional for advice specific to your situation.
💬 Over to you
Did you check your MER after reading this? Tell us the number you found — and whether it changed what you hold.
Share it in the comments below — every comment gets a reply.
Comments
Comments are moderated to keep this page clean: first comments and anything containing a link are checked by a human before they appear, and spam is blocked automatically. Your email is never shown — it only tells the moderator you are a returning reader.
Loading comments…