Earn $110K in Canada? How Much Mortgage Can You Actually Get?
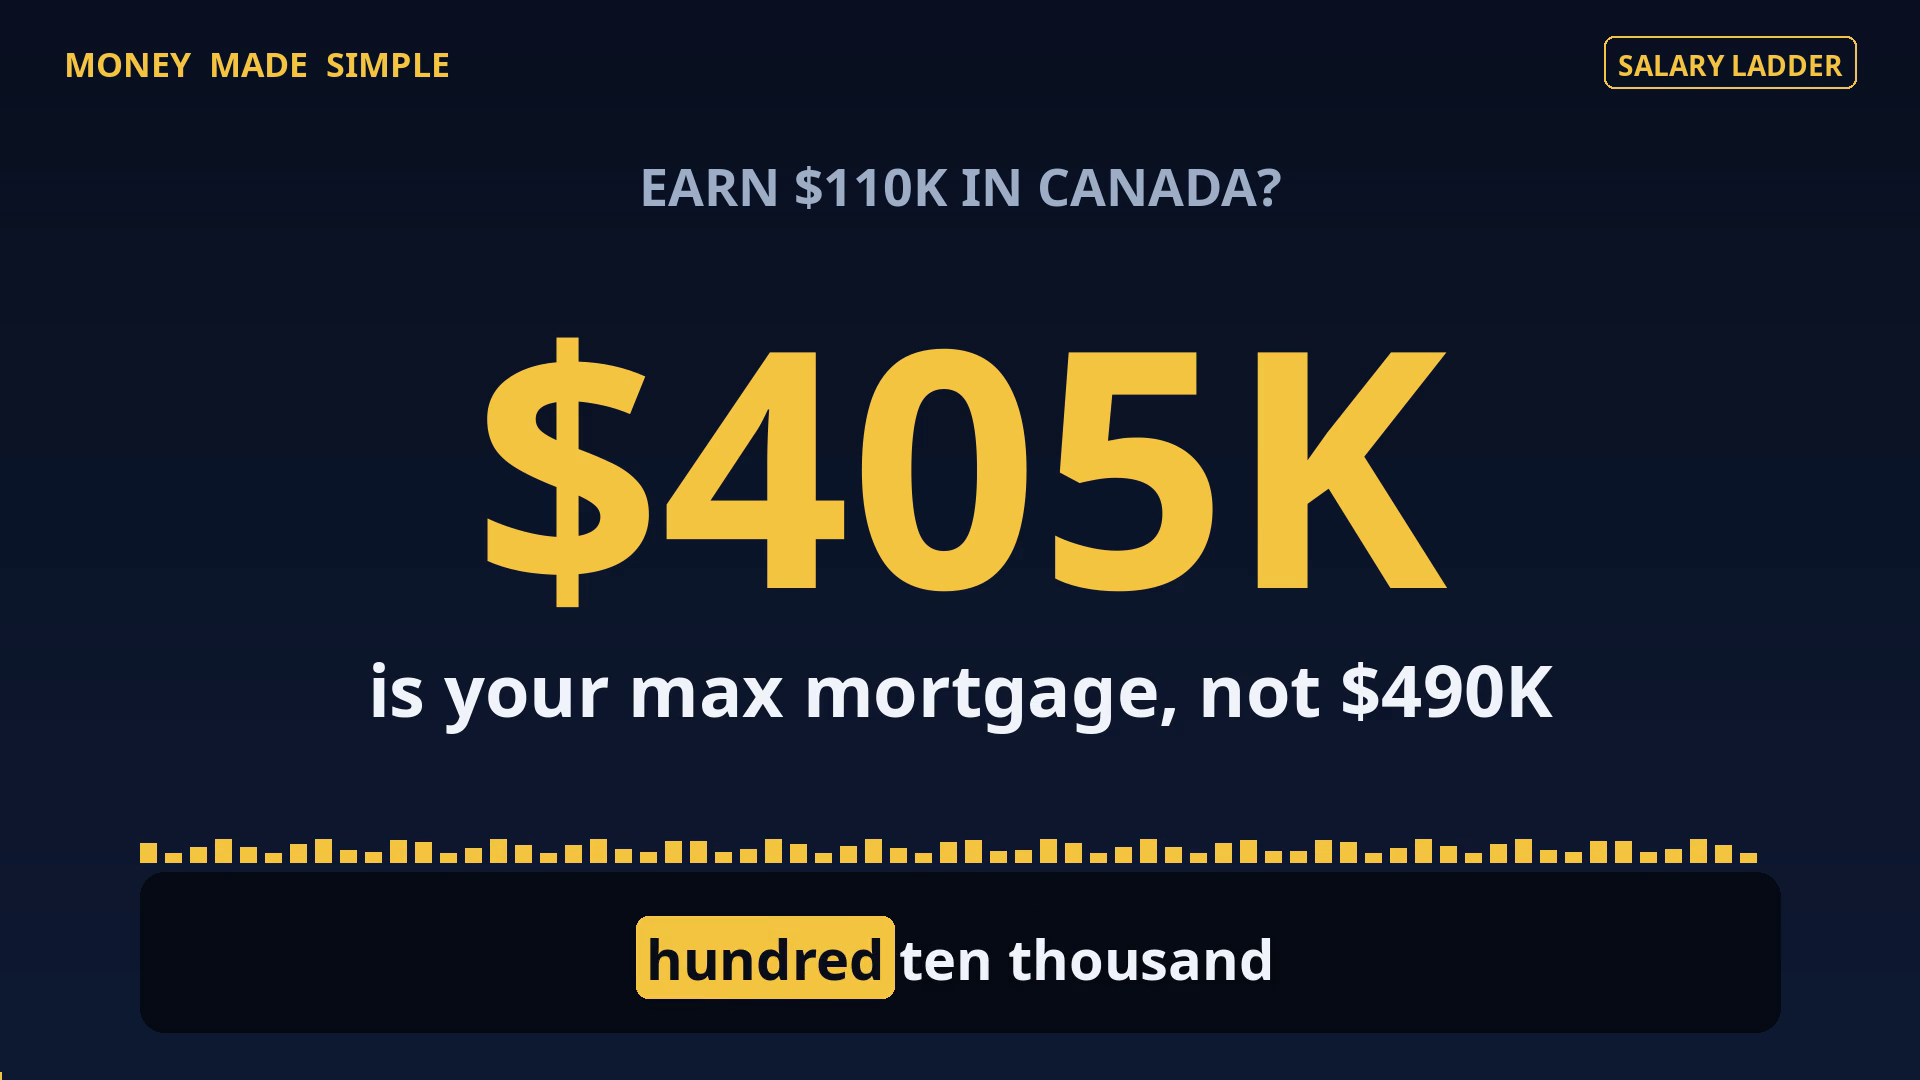
On a $110,000 salary in Canada, the stress test caps your maximum mortgage at $404,701 — not the $489,826 the same payment room would carry without it. After $500 of tax and heating, your payment room is $2,708 a month. The comfortable loan is $308,818 — a home around $386,023.
Earn $110,000 a year in Canada and the down payment alone passes six figures. This is the full written version of Money Made Simple's Canadian Salary Ladder, episode 3: "Earn $110K in Canada? Your Max Mortgage Is $405K" — published November 7, 2026. Every figure below was computed in Python for the episode (figures.json, asserted in the build), not guessed — and you can check each step yourself.
Key takeaways
- On a $110,000 salary, the bank's maximum mortgage in this worked example is $404,701 — not the $489,826 the same payment room would carry without the stress test.
- The stress test costs this salary $85,125 of borrowing power: you must qualify at 6.49% (the example contract rate of 4.49% + 2%), even though you pay at 4.49%.
- Two ceilings decide everything: housing costs under 35% of gross income (GDS) and housing plus all debts under 42% (TDS).
- At this rung the TDS trap moves: $600 a month of other debts still passes with $42 to spare, but $700 a month goes over the ceiling by $58 — declined.
- The bank's maximum is a ceiling, not a target: the episode's comfort number is $308,818, a home around $386,023 with 20% down.
🎁 Free companion for this guide
The free Money Pack pairs with this guide — and Pai Ledger HQ puts it into practice, starting with a free trial.
Step 1: The $110K salary, monthly
Lenders do their math monthly, so start there. A $110,000 gross salary is $9,167 a month before tax. Every ceiling below is a percentage of that one number.
Step 2: Rule 1 — the 35% GDS ceiling
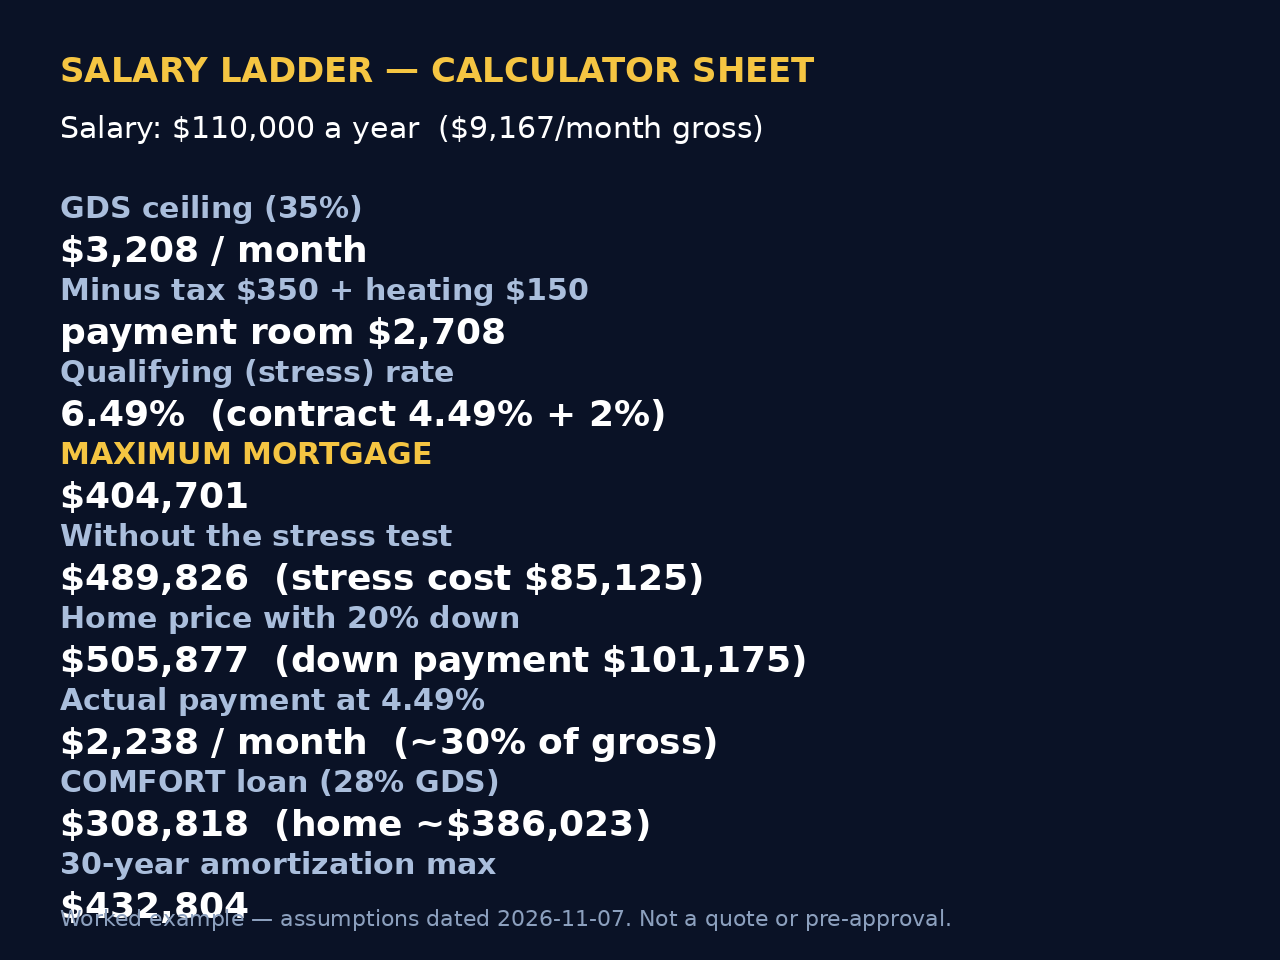
GDS (gross debt service) caps your total housing costs — mortgage payment, property tax and heating — at a share of your gross income. This episode's example uses a 35% GDS ceiling: 35% of $9,167 = $3,208 a month for all housing costs combined. That $3,208 is not your mortgage payment. Tax and heat get paid out of it first.
Step 3: Tax and heating eat $500 of it
The worked example uses $350 a month for property tax and $150 a month for heating — $500 gone before the mortgage payment: $3,208 − $500 = $2,708 a month left for the mortgage payment itself. This is the step most first-time buyers miss: your real payment room is $2,708, not $3,208.
Step 4: Rule 2 — the stress test at 6.49%
Canadian lenders must check that you could still carry the loan at a higher qualifying rate: your contract rate plus 2%, with a floor — whichever is higher. The example contract rate is 4.49%, so the test runs at 6.49%.
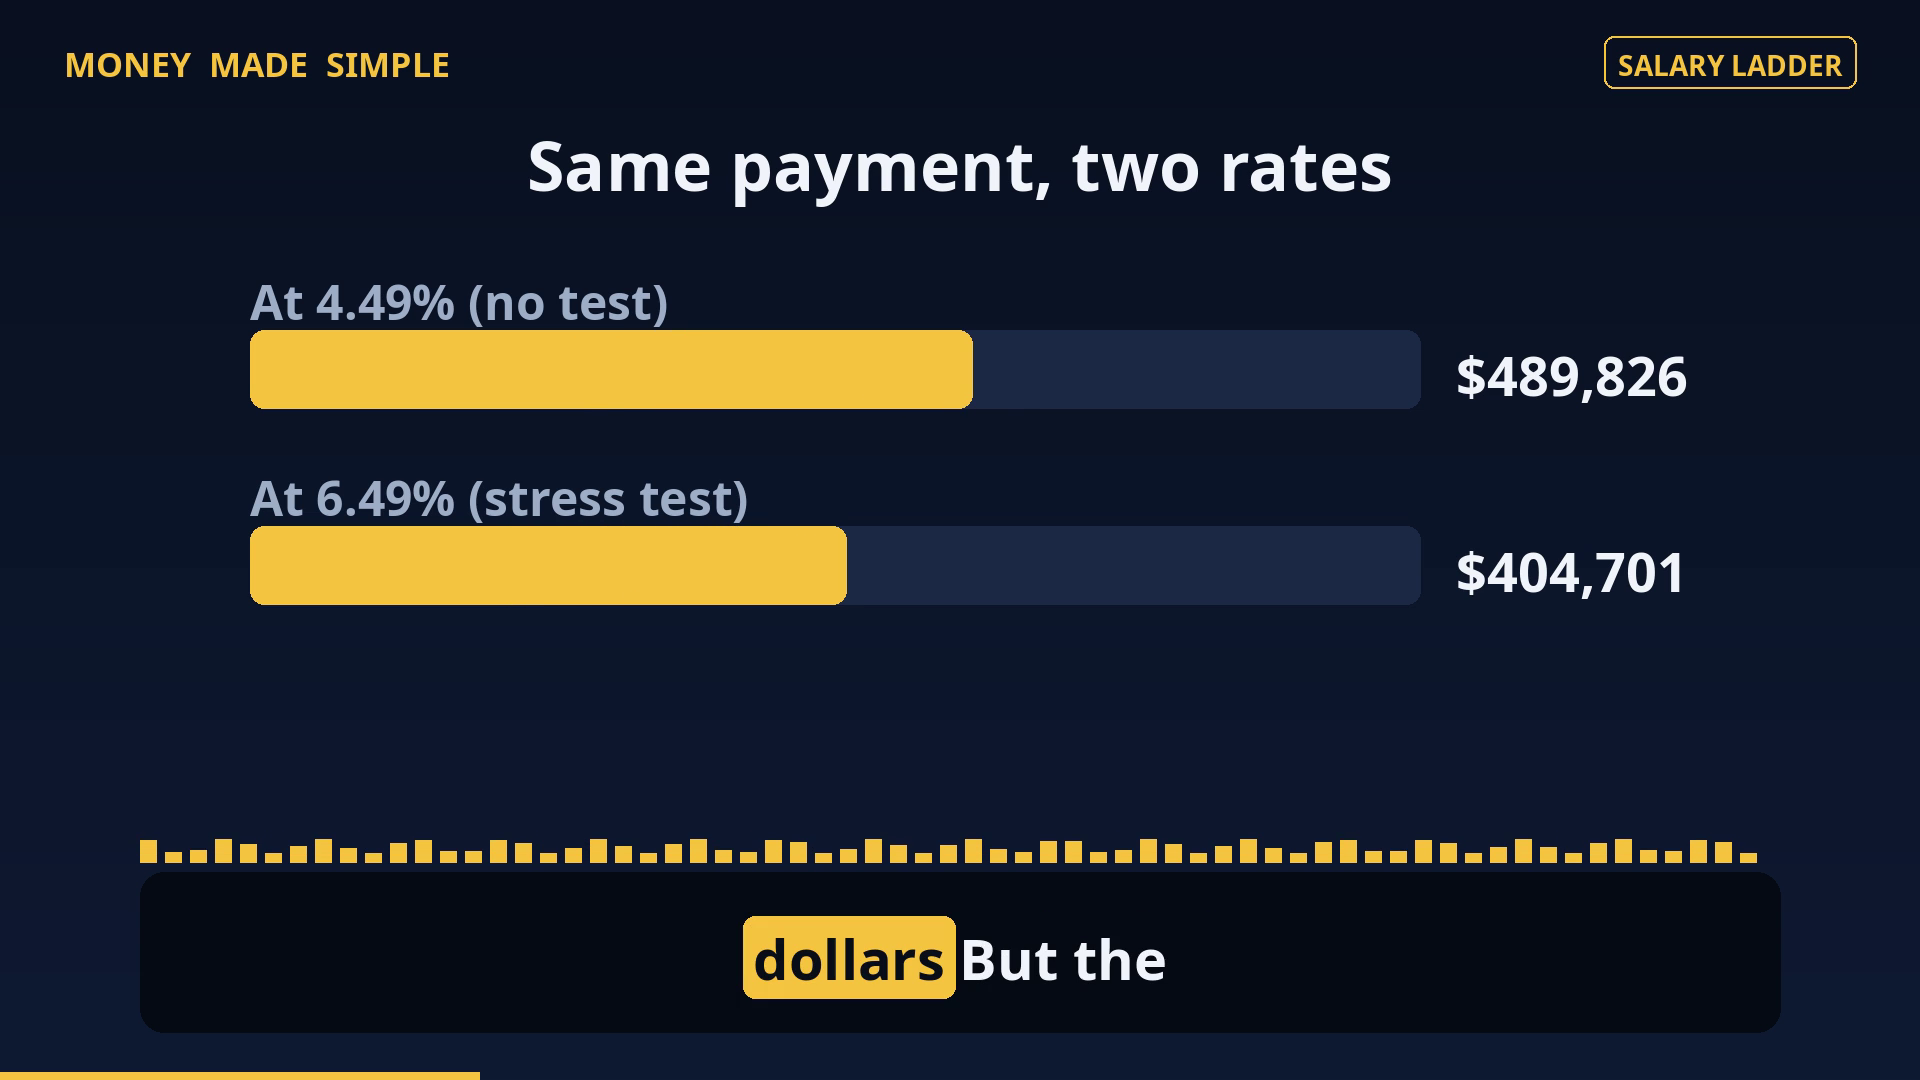
Same $2,708 of monthly room, two very different loans (25-year amortization, Canadian semi-annual compounding): at the 4.49% contract rate, that room would carry $489,826; at the 6.49% qualifying rate, it carries $404,701. The difference — $85,125 — is the borrowing power the stress test removes. You will pay at 4.49%, but the size of your loan is decided at 6.49%. That gap is the whole point of the episode: $405K is the real maximum, not $490K.
Why is this number different from our $100K guide?
Our Max Mortgage on $100K Income in Canada guide includes a $60K–$150K ladder whose math puts a $110K income at about $477,000 — a different number for the same salary, because that guide uses different assumptions: a 39% GDS / 44% TDS ceiling, qualification at 6.25% (a 4.25% example contract rate + 2%), and $450 a month for property tax and heat. This post follows Salary Ladder episode 3 exactly: 35% GDS / 42% TDS, qualification at 6.49% (a 4.49% contract rate + 2%), and $500 a month for tax and heat ($350 + $150) — which gives $404,701. Both are internally correct worked examples; neither is a quote. Compare the assumptions, not just the headline, and run your own lender's numbers.
Step 5: Rule 3 — the 42% TDS debt check, and this rung's trap
TDS (total debt service) is the second ceiling: housing costs plus every other debt payment must stay under 42% of gross income: 42% of $9,167 = $3,850 a month for housing and all debts together.
The episode runs the check three ways, and this rung's story is different from the $90K rung's. With $300 a month of other debts you pass with $342 to spare. Even $600 a month still passes — with just $42 to spare, one tank of gas of room. But at $700 a month the same salary, the same house and the same mortgage go over the ceiling by $58: declined. Nothing about the home changed — the car payment decided the mortgage. Paying down debt before you apply is buying power, dollar for dollar.
Put this into practice: Pai Ledger HQ
Pai Ledger HQ tracks your real payoff date as payments land, and the free Money Pack includes this episode's calculator sheet so you can run the same stress-test math on your own numbers.
Pai Ledger HQ is $6/mo, $61.20/yr or $120 lifetime — or get it inside the All Apps Pass ($72/mo) with every other app.
Step 6: The home price — 20% down, plus closing costs
A $404,701 mortgage at 80% of the price means: maximum home price $505,877; down payment (20%) $101,175 — at this rung the down payment itself passes six figures of cash, saved before you buy; closing costs to budget on top (about 1.5% of price in this example) about $7,588. Saving that down payment at $1,000 a month takes about 101 months — which is why the episode points first-time buyers at the First Home Savings Account, where an $8,000 year of contributions at an example 20% tax bracket could mean about $1,600 of tax back toward the home.
Step 7: What you actually pay each month
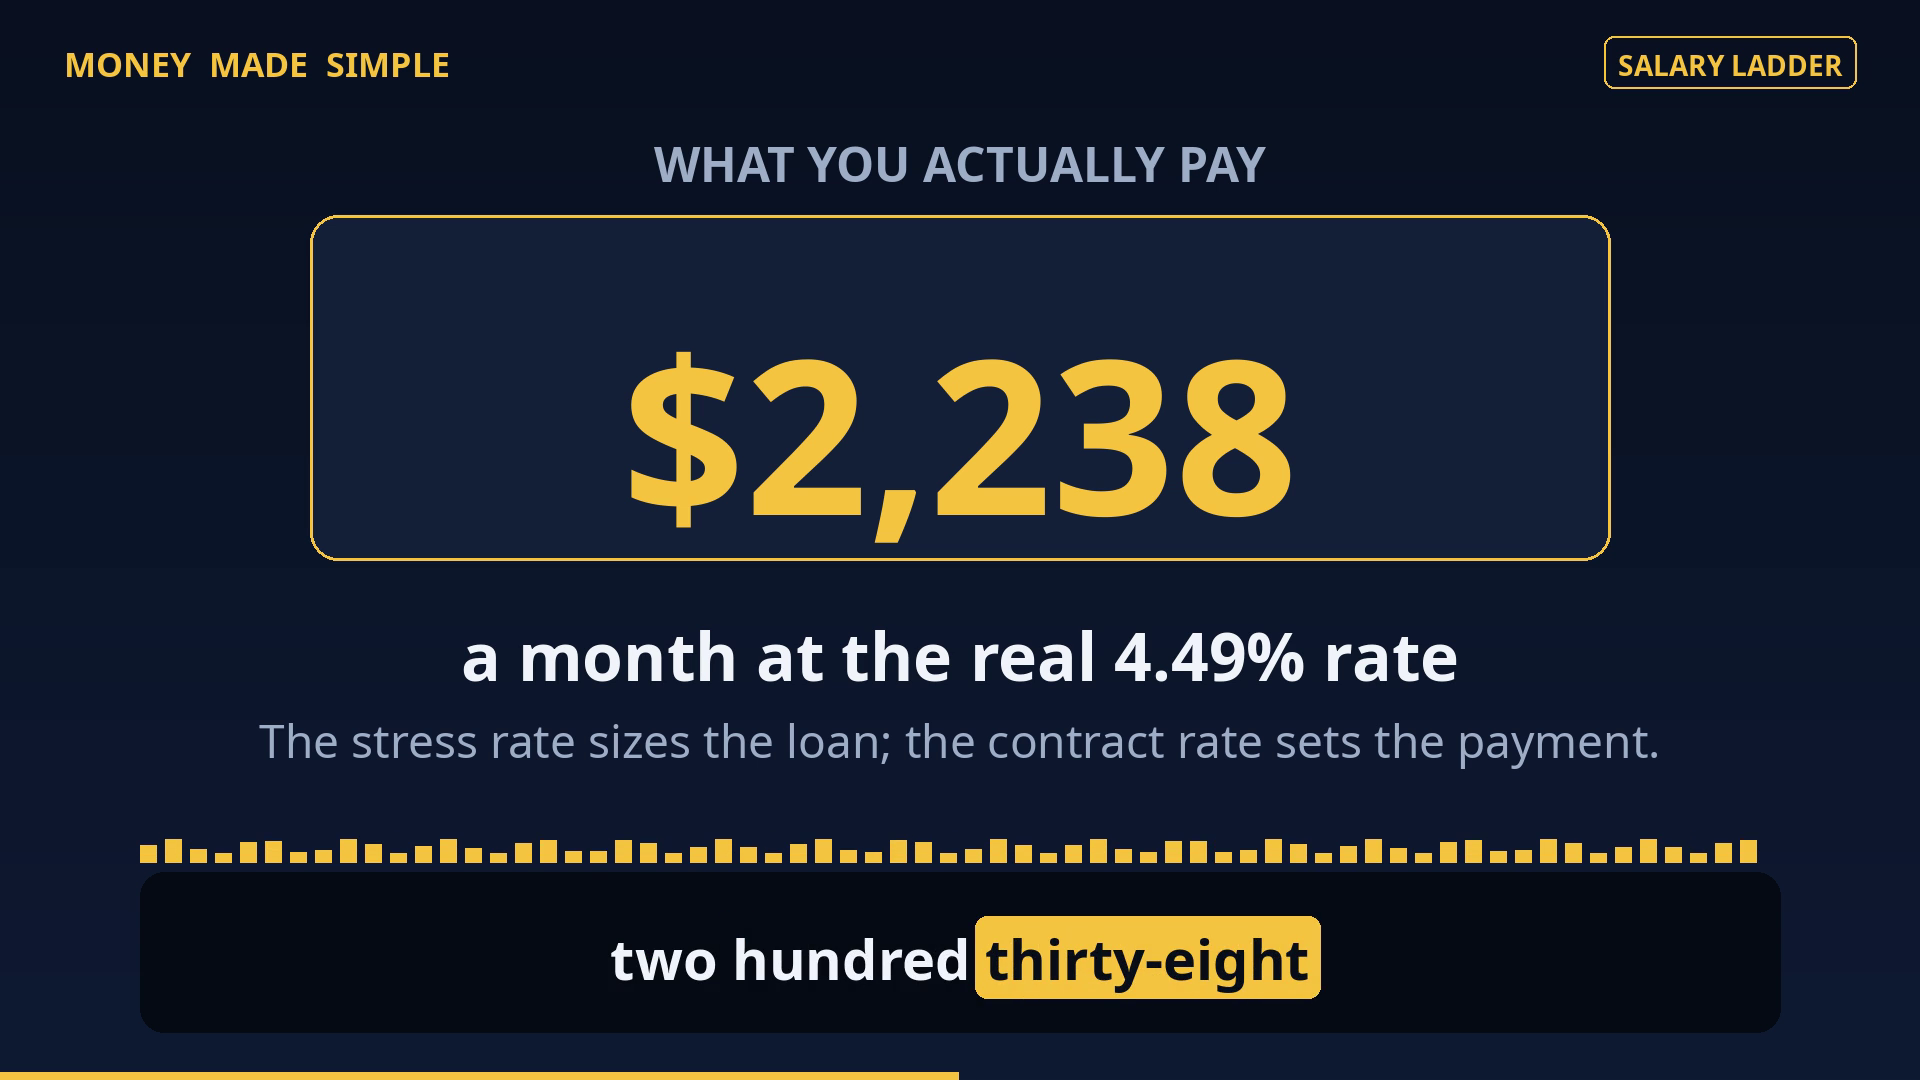
You qualify at 6.49%, but you pay at your contract rate. On the maximum $404,701 loan at the example 4.49% contract rate, the real monthly payment is about $2,238 — and with tax and heating added, true housing cost is about 30% of gross pay. The stress test is a buffer, not your bill.
The comfort number: about $309K
The bank's maximum is a ceiling, not a target. The episode also runs a comfort level at 28% GDS — a loan that leaves room for repairs, savings and life: comfort loan $308,818; comfort home price with 20% down about $386,023. The gap between the maximum and the comfort loan is more than $95,000 — the episode calls it the difference between owning a home and being owned by one. Its repair test makes the point concrete: budget about 1% of the home price a year for upkeep, about $422 a month on this example home.
A legal way to borrow more: 30 years
One lever genuinely moves the maximum: a longer amortization. For eligible first-time buyers and new homes, stretching to a 30-year amortization raises the maximum loan in this example to $432,804 — about $28,000 more, same salary, same stress test, smaller monthly payment at the test rate. The trade-off is five extra years of interest, so it is a tool, not a gift.
Buying a condo? The fee shrinks the loan
Canadian lenders add half of a monthly condo fee to your housing costs. On the episode's example fee of $400 a month, $200 of your payment room is gone and the maximum loan falls to $374,816 — nearly $29,000 less. The salary did not change; the building did. And if rates fell a full point, the test rate would fall with them and the maximum would rise to about $444,128 — your buying power is set by your salary divided by a test rate, and that rate can move your maximum by the price of a car.
Put it into practice
Pai Ledger HQ tracks your real payoff date as payments land, and the free Money Pack includes this episode's calculator sheet so you can run the same stress-test math on your own numbers.
Get the free Money Pack Pai Ledger HQ
Or get every Pai Digital app in one plan: the All Apps Pass — $72/mo, $734.40/yr or $1,440 lifetime, with free trials on every app.
Frequently asked questions
How much mortgage can I get on a $110,000 salary in Canada?
In this worked example, the maximum is $404,701. The assumptions: a 35% GDS ceiling, $350 a month of property tax and $150 a month of heating, a 25-year amortization, and qualification at 6.49% (an example contract rate of 4.49% + 2%). Your lender's number will differ with your real tax, heating, debts and rate.
Why is the qualifying rate 6.49%?
The example contract rate is 4.49%; Canadian rules qualify you at contract + 2% (with a floor), so 6.49% decides the loan size while you pay at 4.49%. At the contract rate the same payment room would carry $489,826 — the stress test removes $85,125 of borrowing power.
What are GDS and TDS ratios?
GDS (gross debt service) caps housing costs — mortgage payment, property tax and heating. This example uses 35% of gross income: $3,208 a month on a $110,000 salary. TDS (total debt service) caps housing plus all other debt payments at 42%: $3,850 a month. Whichever ceiling gives the smaller room is the one that decides your maximum.
How much debt can I carry and still pass at $110K?
In this example, $600 a month of other debt payments still passes the 42% TDS check with $42 to spare, but $700 a month goes over the ceiling by $58 and the same mortgage is declined. The exact trap point moves with your housing costs — run your own debts through the same check.
What home price can I buy on $110K with 20% down?
With 20% down on the maximum mortgage in this example, about $505,877 — with a down payment of $101,175. Budget closing costs on top: about $7,588 in this example, at about 1.5% of the price.
Should I borrow the maximum the bank offers?
The bank's maximum is a ceiling, not a target. At this episode's 28% GDS comfort level, the same salary carries about $308,818 — a home around $386,023 with 20% down, with room left for repairs, savings and life. Your actual payment on the maximum loan would be about $2,238 a month at the example 4.49% contract rate.
How we make these guides
Every guide in this section started as a video on one of our YouTube channels, and the written version is checked against that video's own script before it is published. Account figures are stated with the year they apply to, drawn from the rules published by the CRA — and the worked examples use standard amortization math you can re-run yourself in our free mortgage calculator. We do not invent numbers: if a figure is not in the video or a source the guide names, it is not in the guide. When a rule changes, we update the guide — and the “last verified” date at the top of this page changes with it. Everything here is educational only — not financial, tax, legal or investment advice for your specific situation.
Recommended next reads
 Mortgage & Housing
FHSA Canada: The First Home Savings Account Explained (2026)
The FHSA combines an RRSP-style tax deduction with a TFSA-style tax-free withdrawal for first homes. $8,000 a year, $40,000 lifetime — the full 2026 guide.
 Mortgage & Housing
Max Mortgage on $100K Income in Canada: $427K, Not $500K
On $100K of Canadian household income the max mortgage that passes the stress test is about $427K, not $500K. The $60K–$150K ladder, GDS 39% / TDS 44%, and the $46,000 two-bill trap.
 Mortgage & Housing
Earn $90K in Canada? How Much Mortgage Can You Actually Get?
On a $90,000 salary in Canada, the stress test caps your maximum mortgage at $317,535 — not the $384,325 you could borrow without it. After property tax and heating, your payment room is $2,125 a month. The comfortable loan on this salary is $239,085 — enough for a home around $298,856.
Watch next
Prefer reading? Read the guide: FHSA Canada: The First Home Savings Account Explained (2026)
Disclaimer: This post is for education and information only and is not financial, mortgage, tax or legal advice. Figures are a worked example using the stated assumptions and example rates as of November 2026; they are not a quote, pre-approval or guarantee. Mortgage rules, rates and programs change — speak with a licensed Canadian mortgage professional about your own situation before making decisions.
💬 Over to you
Which ceiling would stop you first at $110K — the 35% GDS limit, the $700-a-month debt trap, or the 6.49% stress-test rate? Run your own numbers on the free calculator sheet and tell us which one you hit.
Share it in the comments below — every comment gets a reply.
Comments
Comments are moderated to keep this page clean: first comments and anything containing a link are checked by a human before they appear, and spam is blocked automatically. Your email is never shown — it only tells the moderator you are a returning reader.
Loading comments…